
EasyBudget - Budget planning
- Rating
- 4.0
- Downloads
- 500.00K
- Content Rating
- Everyone
EasyBudget - Budget planning - Screenshots
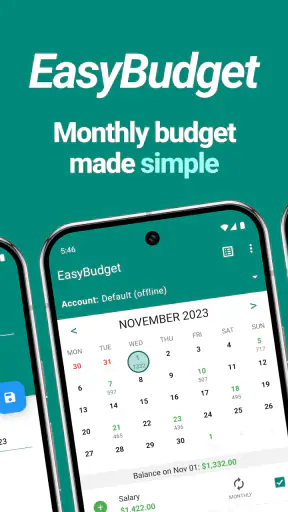
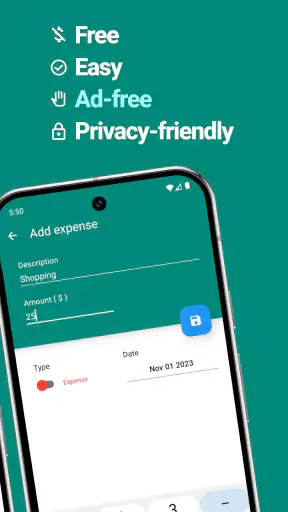
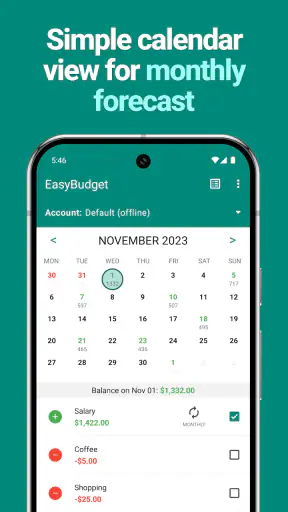
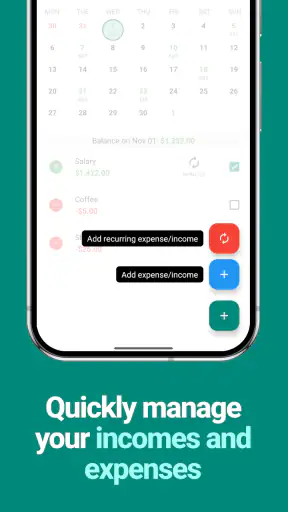
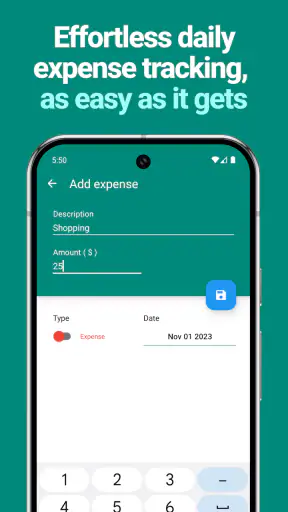
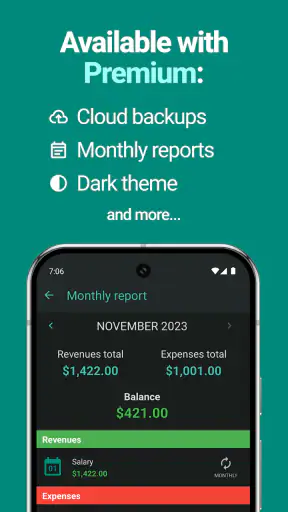
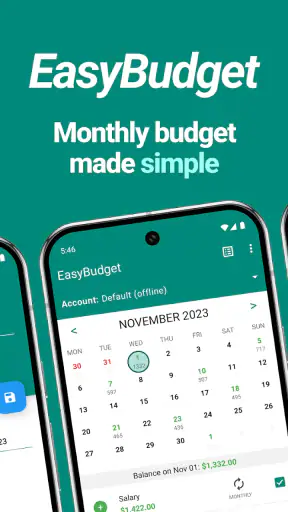
Pros
- Simple interface makes daily expense tracking quick and approachable.
- Flexible categories help organize spending around personal priorities.
- Clear budget overviews make it easier to spot overspending early.
- Useful for tracking multiple income sources and recurring expenses.
- Lightweight design should run smoothly on most modern devices.
Cons
- Some advanced reporting and forecasting tools may feel limited.
- Manual entry can become time-consuming for users with many transactions.
- Category customization may require extra setup before tracking feels natural.
- Budget accuracy depends on consistently recording every purchase.
- Users may miss deeper account-sync features found in larger finance apps.
EasyBudget - Budget planning - Description
- App Name
- EasyBudget - Budget planning
- Package Name
- com.benoitletondor.easybudgetapp
- Developer
- Wallet Passes Alliance
- Category
- Finance
- Last Updated
- Dec 2, 2015
- Version
- 4.1.0
I started using EasyBudget because I wanted a calmer way to plan household spending without turning every purchase into a spreadsheet project. It is a free finance app from Wallet Passes Alliance, designed around monthly budget management rather than investing, banking, or complicated financial forecasting. That focus is its biggest strength: I could think in terms of what was available for the rest of the month instead of staring at a long list of transactions.
My experience also showed me where the app fits best. EasyBudget works well when one person, or a small household, agrees to keep the budget updated manually and consistently. It is less suitable if you expect automatic bank synchronization, detailed shared accounts, or a complete replacement for a professional money-management service. The interface feels approachable, but the quality of the result depends heavily on the habits of the people using it.
How EasyBudget works in a real household
A practical shared-device routine
The most useful way I found to use EasyBudget was on a shared household device, with one person taking responsibility for keeping the monthly figures current. For example, after payday, I would set aside the regular categories first: groceries, transport, utilities, subscriptions, and flexible spending. When someone bought something for the home, we could record it during the same conversation rather than relying on memory at the end of the week.
That small routine matters more than it sounds. A budget app can be beautifully designed and still fail if purchases are entered several days late. EasyBudget’s simple approach makes quick updates less intimidating, which is helpful when a partner is not interested in learning a complex finance system. The app becomes a shared reference point: before ordering takeout or buying something nonessential, we could check the remaining amount for that part of the month.
I would not treat a shared device as proof that everyone has the same access or responsibility. If the phone or tablet is passed around, decide in advance who may edit the figures and who is only checking them. EasyBudget is a budgeting tool, not a substitute for an agreement between household members. Clear expectations prevent the common problem where one person assumes an expense was recorded while another assumes someone else handled it.
What to decide before entering numbers
The first useful step is not typing in every expense. It is deciding what the monthly budget is supposed to represent. I found it easier to begin with the money available for ordinary spending, then separate fixed commitments from categories that can change. That makes the remaining amount more meaningful than a single total that mixes rent, groceries, and occasional purchases.
For a shared household, I recommend agreeing on category names before building the routine. “Food,” “groceries,” and “eating out” can become confusing if different people use them interchangeably. A short list that everyone understands is better than a detailed structure that nobody maintains. The app’s accessible design supports this kind of straightforward planning, but it cannot resolve disagreements about how a purchase should be classified.
Another useful boundary is deciding whether the budget covers the whole household or only discretionary spending. If it includes every bill, the monthly picture may be more complete. If it is intended only for flexible purchases, the remaining figure can be easier to interpret. Neither approach is automatically right; the important point is to avoid changing the meaning halfway through the month.
Keeping account boundaries clear
EasyBudget is best used as a planning layer rather than as a shared bank account. I would not enter sensitive banking credentials into a routine built around manual household coordination, and I would not assume that recording a purchase changes the balance in a real account. The app helps you decide what you can afford; your bank or payment service remains the place to verify what has actually cleared.
This distinction is especially important when several people use one device. A child might be allowed to view a household spending target, while only an adult should change the monthly plan. A roommate might need to report shared purchases but should not be expected to manage another person’s private spending. The cleanest arrangement is to use the app for agreed household figures and keep personal financial details outside the shared routine.
Because EasyBudget is rated for Everyone, its presentation is approachable for a wide range of users. That does not mean every financial decision should be delegated to a younger household member. Age-appropriate guidance still matters, particularly when the figures relate to rent, debt, income, or essential bills. I see the age rating as a sign that the app is broadly accessible, not as a replacement for adult supervision or financial education.
Coordinating without creating arguments
A budget becomes much more useful when it reduces friction instead of creating a new reason to argue. I found that discussing the category before entering an unusual purchase worked better than correcting it later. A household might agree that a birthday gift belongs in a separate occasional category, for instance, rather than letting it make the grocery budget look unexpectedly poor.
For shared use, I would establish a simple reporting rule: record household purchases immediately, mention cash spending at the end of the day, and review the remaining flexible amount together once or twice during the month. This is more realistic than demanding constant financial meetings. EasyBudget’s uncomplicated purpose makes it suitable for that lightweight process, especially for people who would abandon a more elaborate app.
One non-obvious advantage of a manual system is that it forces a conversation about spending. Automatic tracking is convenient, but it can also make purchases disappear into a feed that nobody reviews. With EasyBudget, entering an expense creates a natural pause. That extra effort is a weakness if you want effortless automation, but a strength if your goal is to make household choices more deliberate.
Where the simple approach helps
I liked EasyBudget most when I needed a quick monthly overview rather than a financial archive. Its free price makes it easy to try without committing the household to another subscription, and the app has attracted over 500,000 installs. The average rating is 4.0 from around 21,000 ratings, which suggests that many people find the basic idea useful while also leaving room for mixed experiences.
The app belongs in the finance category, but it should not be confused with a full banking dashboard. I would choose it for setting limits, checking available spending room, and building awareness around recurring household habits. I would look elsewhere for investment tracking, tax preparation, detailed debt planning, or a system that automatically gathers transactions from several institutions.
That comparison is important because many budgeting alternatives promise a broader view of personal finances. A spreadsheet gives you more control and can be tailored to complex households, but it requires more setup and maintenance. A bank’s own tools may show current transactions more automatically, although they may not offer the same simple monthly planning mindset. EasyBudget sits between those options: less demanding than a custom spreadsheet, but more dependent on manual discipline than an integrated banking service.
Using it with different ages and levels of trust
For teenagers learning the basics of monthly spending, EasyBudget can provide a clear visual habit: decide on an amount, record purchases, and notice how choices affect what remains. I would use it as a teaching aid, not as a way to monitor every small decision. A young user can learn the difference between planned and unplanned spending without being given access to private household information.
For older relatives, the straightforward presentation may be less overwhelming than a finance app filled with charts, account connections, and technical terminology. Still, I would set it up together and explain what each figure means. If someone has difficulty entering expenses, another trusted adult should help maintain the record rather than assuming the numbers will remain accurate on their own.
Trust also matters between adults. If one person quietly changes categories or adjusts the monthly amount, the app can give a false sense of agreement. I recommend treating edits as part of the household conversation. The tool is useful precisely because it makes the plan visible, but visibility only helps when everyone understands which numbers are estimates, which are commitments, and which are already spent.
Version, compatibility, and the cost question
The current version is 4.1.0, and it runs on Android 7.0 or later. That makes it accessible on many older Android devices, which is helpful if a household keeps a spare phone or uses an older tablet as a shared planning screen. I would still check the device experience personally before moving the whole household to it, because ease of use depends on screen size, typing comfort, and who is responsible for updates.
There is no purchase required to start using the app. Optional in-app purchases range from $0.99 to $99.99 per item, so I would review any purchase screen carefully before confirming anything, especially on a shared device. This is another reason to establish account boundaries: the person maintaining the budget should know whether optional paid items are appropriate, while children or guests should not be left to make that decision accidentally.
The Everyone content rating is reassuring for general household access, but it does not make the app a family-control product. I would not expect it to manage allowances, enforce spending limits, create separate child profiles, or coordinate permissions unless those functions are clearly available in the version being used. For those needs, a dedicated family finance service would be a better match.
Small workflows that make the app more reliable
My first practical tip is to enter the monthly plan before recording individual purchases. Without that starting point, the app can become a diary of spending rather than a budget. Once the categories are established, every entry has context, and the remaining amount can guide decisions instead of merely describing the past.
My second tip is to separate predictable commitments from flexible choices. A household bill should not compete visually with an optional purchase, because the consequences are different. Even if the app remains simple, this distinction helps everyone understand which amounts are already spoken for and which ones can be adjusted.
My third tip is to use a short weekly check rather than waiting for a crisis near the end of the month. Look for categories that are moving faster than expected, then make a small correction while there is still time. This is where a simple app can outperform a neglected spreadsheet: the lower effort makes a brief review more likely to happen.
A fourth useful habit is to record shared purchases with enough detail for the next person to recognize them, but not so much detail that entry becomes a chore. “Household supplies” may be sufficient for a routine purchase, while a large one-off item deserves a clearer note in whatever way the app allows. The aim is future understanding, not perfect accounting.
Limitations I noticed during everyday use
The same simplicity that makes EasyBudget approachable can feel restrictive for people who want deep analysis. If you need extensive reports, sophisticated forecasting, or automatic reconciliation, a spreadsheet or a more advanced finance platform will probably serve you better. EasyBudget is not trying to be a complete financial command center, and expecting it to behave like one leads to disappointment.
Manual entry is another real trade-off. It gives the household control over what is included, which can be useful when privacy matters, but it also creates opportunities for forgotten purchases and inconsistent categories. The app cannot know that someone paid cash, used a different card, or made a purchase while the shared device was unavailable unless a person records it.
Shared use can also become awkward if several people want independent budgets. One household may need a combined monthly plan, while another may want separate personal limits plus a shared grocery amount. EasyBudget can be a good fit for the combined view, but I would not choose it as the only tool when strict separation between users is essential. In that situation, individual accounts or a purpose-built family finance system would provide clearer boundaries.
Who should choose it, and who should skip it
I would recommend EasyBudget to someone who wants a low-pressure monthly planning tool, especially if a household is willing to update it manually. It suits a couple coordinating everyday spending, a parent teaching a teenager how categories work, or a roommate group that needs a shared reference for agreed expenses. The free entry point also makes it reasonable to test the routine before investing time in a more elaborate system.
I would skip it if your main requirement is automatic transaction collection, detailed financial reporting, or separate permissions for every household member. I would also look elsewhere if you need budgeting tied directly to investment accounts, formal bill management, or professional financial records. Those are not minor preferences; they change the kind of product you need.
For me, the deciding question is whether I am willing to maintain the numbers. If the answer is yes, the app’s straightforward structure keeps monthly planning visible without adding much complexity. If the answer is no, its simplicity cannot compensate for missing entries. That is the central trade-off: EasyBudget reduces the learning curve, but it does not remove the responsibility to keep the plan honest.
My household verdict
After using it as a shared planning aid, I see EasyBudget as a sensible choice for households that want coordination without turning money management into a technical project. Wallet Passes Alliance has kept the focus on monthly budgeting, and that narrow purpose is exactly why the app can feel comfortable for first-time budgeters. I could explain the routine to another person quickly, which is valuable when not everyone enjoys finance apps.
I would keep account boundaries explicit, agree on category meanings, and treat the app as a planning record rather than a live bank balance. Those steps make the experience more dependable and reduce misunderstandings between adults, children, and other people sharing the device. The app is especially useful when the household wants to discuss spending before it becomes a problem.
My final view is positive but conditional: EasyBudget is strongest when simplicity and shared awareness matter more than automation and advanced control. It is free to begin, available for Everyone, and practical for an agreed monthly routine. If that describes your household, I think it is worth trying. If you need separate financial identities, automatic imports, or detailed analysis, choose a more specialized alternative instead.
FAQ
What is EasyBudget - Budget planning used for?
EasyBudget - Budget planning is designed to help you organize personal finances by recording income, expenses, and spending categories in one place. After reviewing its main functions, the app appears most useful for people who want a simple overview of where their money goes, plan upcoming costs, and maintain better control of monthly or weekly budgets without relying on complicated financial tools.
Is EasyBudget - Budget planning suitable for beginners?
Yes, EasyBudget - Budget planning is generally suitable for beginners because its purpose is straightforward: enter your financial information, assign expenses to categories, and compare your spending with your available budget. Users who have never used a budgeting app should be able to understand the basic workflow quickly, although creating accurate categories and consistently adding transactions is still important for getting reliable results.
Does EasyBudget - Budget planning require an internet connection?
The app’s core budgeting tasks may be usable without a constant internet connection, depending on the version and device settings. However, some features can require connectivity, particularly updates, synchronization, account-related services, advertisements, or cloud-based functions. Before downloading, users should check the current Google Play or App Store listing to confirm offline availability and whether their data is stored locally or synchronized online.
Is my financial information safe in EasyBudget - Budget planning?
As with any personal finance application, users should review EasyBudget - Budget planning’s privacy policy and requested permissions before entering sensitive information. A budgeting app normally handles details such as transactions, categories, and financial goals, but it should not be treated like a bank account unless clearly stated. Avoid entering banking passwords, card PINs, or unnecessary identifying information, and use device security such as a screen lock.
Is EasyBudget - Budget planning free to download and use?
EasyBudget - Budget planning may be available as a free download, but the exact pricing model can vary by platform, region, and app version. Some features may include advertisements, optional purchases, subscriptions, or limits on categories and budgeting tools. Check the store page carefully before installing, especially the in-app purchase section, so you understand which functions are included at no cost and which require payment.


